Virtual fiduciary financial advisors are reshaping the financial services landscape by providing professional guidance through digital platforms while maintaining a legal and ethical commitment to act in their clients’ best interests. As technology continues to influence how individuals manage their finances, virtual advisory models are becoming increasingly popular among investors, retirees, business owners, and families seeking convenient access to financial expertise. These services combine personalized planning with digital accessibility, helping clients make informed decisions regardless of location.
Weekly Brief
×Be first to read the latest tech news, Industry Leader's Insights, and CIO interviews of medium and large enterprises exclusively from Financial Services Review
Top Virtual Fiduciary Financial Advisors 2026
Virtual fiduciary financial advisors provide remote guidance designed to prioritize clients’ financial interests. With a focus on planning clarity, investment oversight, risk alignment and digital accessibility, they support more informed financial decisions and stronger long-term wealth management.
Solutions
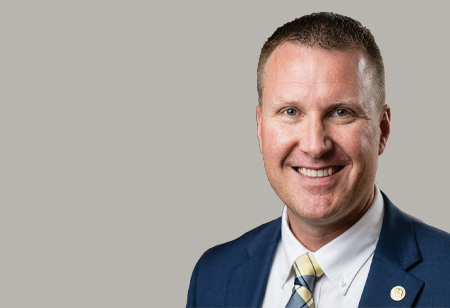
Schutte Financial
Building Wealth with Purpose
Daniel P. Schutte, Founder
No two individuals and families approach financial planning with exactly the same priorities. Some may be preparing for retirement, another focused on preserving wealth for future generations, while others may wish to support charitable causes or build greater financial freedom.
State of Industry
Deep Dive
Choosing Wealth Guidance When Advice Carries Hidden Incentives
The most important wealth-management decisions often happen before a portfolio is ever built. Executives comparing advisory firms are not just choosing someone to manage investments. They are deciding who will influence retirement income, tax strategy, insurance decisions and legacy planning when those priorities sometimes compete with one another and require careful trade-offs. A portfolio may appear well constructed, yet hidden fee structures or product incentives can gradually steer recommendations away from the client’s long-term goals. The real question is not whether an advisor offers a wide range of services, but whether those services are guided by the client’s objectives instead of a product lineup.
Leadership Perspective
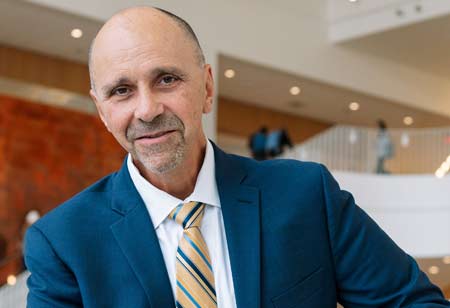
Voya Financial [NYSE: VOYA]
The Importance of Organizational Alignment: Strategy, Environmental Understanding, and Unifying Processes for Success
Michael Dotto, Director
Organizational alignment is bringing the organization's overall success vision and how its executives and other stakeholders contribute to achieving those objectives in harmony (Sousa et al., 2014). A clear and aligned business model emphasizes the importance of teamwork and clear communication. Most people in any business are aware of the short- and long-term company strategy, procedures, and goals when there is organizational alignment. Aligning organizational strategy and structure may aid in focusing resources on important goals. This high level of organizational cohesion is achievable with careful planning, open communication, and thoughtful management. Businesses usually use it to achieve results that are urgently needed, but it can also be focused on longer-term corporate objectives. This paper explains the reasons why there needs to be an alignment of the organizational values, purposes, goals, objectives, and strategy, how an understanding of environmental issues, for instance, unchangeable structure, government regulations, and limits of personnel and finance have an impact in making strategy and finally address how making a strategy can perhaps be a unifying process building community, identity and the organizational commitment in the organization.
Virtual Fiduciary Financial Advisors News
Virtual Fiduciary Advice Moves into Mainstream Wealth Planning
Thursday, August 27, 2026
Virtual fiduciary financial advisors are gaining stronger relevance as clients become more comfortable receiving financial planning, investment guidance and retirement support through digital channels. The market is no longer defined by the choice between a local advisor and a fully automated robo platform. It is moving toward hybrid advisory models that combine remote access with fiduciary responsibility.
Digital advice is expanding because clients want convenience without losing trust. The Business Research Company describes hybrid robo-advisory as a model that combines automated portfolio tools with access to human financial advisors, with services ranging from goal-based planning to comprehensive wealth advisory.
This shift is important for fiduciary advisors because remote delivery can widen access. Clients who live outside major financial centers, travel frequently or prefer digital meetings can still receive structured advice. For advisory firms, virtual service models also allow advisors to serve more households without relying on branch-heavy infrastructure.
The fiduciary element remains central. Registered investment advisers are expected to serve their customers in good faith and reveal material facts. The latest compliance guidance for RIAs stresses fiduciary requirement, conflicts, disclosure and compliance programs.
This makes it easier for virtual advisors to distinguish themselves in the market compared to generic financial information or sales-oriented services. While the customer can discover investment tips via the Internet, the fiduciary advisory relationship demands the provision of customized advice.
Virtual advisory is also leading to a shift in terms of pricing structures in the industry. Fee-based planning, subscription plans and hybrid digital advice have started making inroads. This can help clients understand what they are paying for, especially when the advisor provides planning beyond portfolio allocation.
However, virtual delivery raises its own expectations. The clients will require safe onboarding, documents gathering, ID validation and scheduling processes. There are requirements for advisory firms for recordkeeping, suitability and communication management systems. Poorly executed virtual delivery process can lower trust levels even in case of qualified advisors.
Client experience will be a differentiation factor. Virtual fiduciary advisor will have to make the complicated financial planning look easy without using face-to-face interaction. That will require well-executed digital platforms, review processes and communication procedures.
The competition in the industry will also be growing. Big wealth management companies, fintechs and independent RIAs are creating remote advisory businesses. There are several models described by WSJ Buy Side in their 2026 overview of fiduciary advisory firms.
The next phase of virtual fiduciary advice will likely favor firms that combine accessibility with disciplined planning. Convenience is important to clients, but they also want assurance that the advice they receive is in their best interest.
Virtual fiduciary financial advisors are now part of the mainstream in wealth management. The key for these new advisors is whether they can provide trusted advice online.
AI Raises New Compliance Questions for Virtual Fiduciary Advisors
Thursday, August 27, 2026
The virtual fiduciary financial advisor is being redefined by artificial intelligence as advisory firms utilize digital means to serve clients in advising, portfolio management and financial planning. Artificial intelligence has potential in making remote advising easier and efficient, but raises challenges regarding supervision and the nature of advice provided.
AI has become a major concern for advisory compliance teams. A recent survey reported by Barron’s found that 85 percent of RIA compliance professionals identified AI as a top issue, ahead of cybersecurity at 37 percent. The same report said many firms have adopted AI policies, approved tool inventories and governance committees.
This matters because fiduciary duty does not disappear when software assists the advisor. If a platform generates a recommendation, the firm still needs to understand whether the output is suitable for the client and consistent with the advisor’s duty of care. Automation can support advice, but it cannot replace accountability.
This problem is also being considered in academic papers. For example, in a 2025 article on the use of AI in financial planning, it is pointed out that robo-advisors can help increase accessibility and lower costs; however, poor regulation could lead to the repetition of the issue of information asymmetry and misaligned incentives.
For virtual fiduciary advisors, this creates a practical design challenge. AI tools may help summarize meetings, draft financial plans, classify client questions or model portfolio scenarios. Each use case needs controls. Firms must know where AI is being used, what data enters the system and how outputs are reviewed.
The SEC’s standards-of-conduct bulletin emphasizes that investment advisers and financial professionals must understand the investment or strategy they recommend so that they can form a reasonable basis for advice to retail investors. That principle becomes more important when advisors use AI-supported analysis.
There is also a risk of over-personalization. AI can create recommendations that appear tailored, but a polished output may hide weak assumptions or incomplete client data. Virtual fiduciary firms must ensure that digital planning tools are grounded in verified facts rather than inferred preferences.
Testing will become more important. A 2026 research paper on auditing artificial intelligence investment recommendations posits that artificial intelligence investment recommendations should first be tested for their suitability as a financial recommendation with regards to portfolio restrictions and commissions before returns are examined.
The best virtual advisory companies will definitely make artificial intelligence a controlled advisor, not an unsupervised one. The role of humans is indispensable in reviewing recommendations, explaining trade-offs and justifying the reasonableness of the recommendations.
The next phase of virtual fiduciary advice will reward firms that can make AI useful without weakening compliance. Efficiency will matter, but trust will matter more.
Virtual fiduciary financial advisors are becoming AI-enabled advice providers. Their strongest value will come from combining a digital scale with human oversight, clear policies and defensible client-specific recommendations.
Hybrid Virtual Advice Strengthens Demand for Human Planning
Thursday, August 27, 2026
Virtual fiduciary financial advisors are seeing stronger demand because clients want digital convenience without giving up human judgment. Automated advisory services can perform tasks of the financial portfolio, yet there is a considerable number of people who require assistance regarding their retirement timing and other important financial activities.
The study on robo-advice and digital financial literacy in Italy showed that robo-advice can be used as an additional source of advice along with independent professional human consultation. The factors of digital financial literacy and digital financial confidence are also important when using robo-advice services.
This points to a wider market pattern. Clients may accept digital onboarding, online planning dashboards and automated portfolio rebalancing, but they often want a human fiduciary when decisions become personal. A retirement distribution plan, business sale or inheritance decision cannot be solved through allocation alone.
The CFP Board’s 2026 Financial Outlook Survey was based on responses from 541 CFP professionals and examined client sentiment, challenges and recommended strategies. The report emphasizes that planning is built through open conversations about goals, challenges and a path toward financial health.
Virtual fiduciary advisors are well-positioned for this environment because planning conversations can happen through video, secure portals and scheduled digital reviews. The advisor does not need to sit across a physical table to understand a client’s concerns. The quality of discovery, analysis and follow-through matters more than location.
The hybrid model also helps serve clients at different wealth levels. Fully bespoke wealth management may remain expensive. Fully automated platforms may feel too limited for clients with complex circumstances. A virtual fiduciary model can sit between those options by using technology for efficiency and human professionals for judgment.
Wealth management trends for 2026 also point toward more technology-enabled advice. Oliver Wyman identifies AI-driven advice, embedded wealth and new distribution models as forces shaping wealth management. The firm also argues that firms need operating playbooks and stronger readiness for market disruption.
Client trust will remain the hardest part to scale. The virtual advisor should be able to explain the fees charged and communicate effectively during market uncertainty. While digital access makes it easy for communication, it raises the expectation of quick responses.
The advisory firms will have to train their employees differently. This is because an effective virtual advisor should have technical planning skills and also be digitally literate in terms of communication. Remote advice will seem far if meetings are not well prepared.
The next phase of hybrid advice will likely favor firms that use technology to make human planning more consistent. The goal is not to replace the advisor, but to make the advisory process easier to access and easier to document.
Virtual fiduciary financial advisors are becoming hybrid planning partners. Their value will be measured by whether they can combine digital convenience with trusted human guidance for decisions that require context, judgment and accountability.
Virtual Fiduciary Financial Advisors Info
Q1
What Do Top Virtual Fiduciary Financial Advisors Do?
Top Virtual Fiduciary Financial Advisors help people plan their finances and manage investments through secure online platforms while always acting in their clients' best interests. Their services often include retirement planning, investment management, tax planning, estate planning, cash flow analysis and regular portfolio reviews. Working virtually allows clients to receive professional advice from anywhere, meet through video calls, access information through online portals and securely share important financial documents.
Q2
What Services Are Typically Offered by Top Virtual Fiduciary Financial Advisors?
The scope of services varies, but Top Virtual Fiduciary Financial Advisors generally provide comprehensive financial planning rather than focusing on a single investment product. Clients may receive retirement income planning, education funding strategies, insurance reviews, risk management guidance, investment portfolio oversight and long-term wealth planning. Many also help clients navigate major life events such as career changes, business ownership, inheritance planning or preparing for retirement, with recommendations designed to support evolving financial goals.
Q3
Why Is Demand for Top Virtual Fiduciary Financial Advisors Growing?
Demand for Top Virtual Fiduciary Financial Advisors is growing as more people want professional financial guidance without being limited by location. Secure communication tools have made it easier to build long-term relationships remotely, while changing work habits have increased comfort with virtual financial services. Many clients also prefer the convenience of scheduling online meetings, reviewing their financial information through secure portals and staying connected without visiting a physical office.
Q4
How Should Individuals Evaluate Virtual Fiduciary Financial Advisors?
Choosing among Top Virtual Fiduciary Financial Advisors involves evaluating several factors beyond investment performance. Individuals should understand whether the advisor consistently operates under a fiduciary standard, review professional credentials, assess experience with similar financial situations and examine the planning process. Fee transparency, communication style, cybersecurity practices, availability of ongoing reviews and the ability to explain recommendations clearly also contribute to a productive long-term advisory relationship.
Q5
What Value Do Virtual Fiduciary Financial Advisors Provide?
Top Virtual Fiduciary Financial Advisors help clients make informed financial decisions while aligning recommendations with personal objectives, risk tolerance and long-term priorities. Comprehensive planning can improve financial organization, support disciplined investing and help individuals prepare for significant life transitions. By considering multiple aspects of a client's financial picture rather than isolated transactions, fiduciary advisors can help reduce avoidable financial mistakes and provide greater confidence when navigating changing economic conditions.
Q6
How Are Technology and Expertise Shaping Virtual Fiduciary Financial Advice?
Technology continues to expand the capabilities of Top Virtual Fiduciary Financial Advisors through secure client portals, digital planning tools, portfolio reporting systems and encrypted communication platforms. These technologies improve efficiency, but professional expertise remains central to the advisory relationship. Experienced advisors interpret financial information, adapt strategies to changing circumstances and provide personalized guidance that technology alone cannot replace. The combination of fiduciary responsibility, professional judgment and modern digital capabilities continues to shape the future of virtual financial advice.
